 Life insurance & IUL for America's linemen
Coverage that doesn't clock out
Life insurance you own — not your local, not your contractor. It stays with you between jobs, flexes with storm-season overtime, and builds cash value while it protects your family.
Free quote for America's linemenQuestion 1 of 5See what you qualify for
A few quick taps. Takes about two minutes — free, no obligation.
- Takes about 2 minutes
- No SSN or payment info
- No obligation
Journeymen, apprentices, groundmen and foremen — union or non-union, utility, co-op or contractor. We're not affiliated with any union, local or utility. Private insurance — not a government program.
Rather talk? Call (202) 365-3584- Proudly serving America's linemen
- Licensed in 49 states
- Free quote in 2 minutes
- No cost, no obligation
- Real agents in Dallas, Texas
Thank you for what you do
America runs on linemen
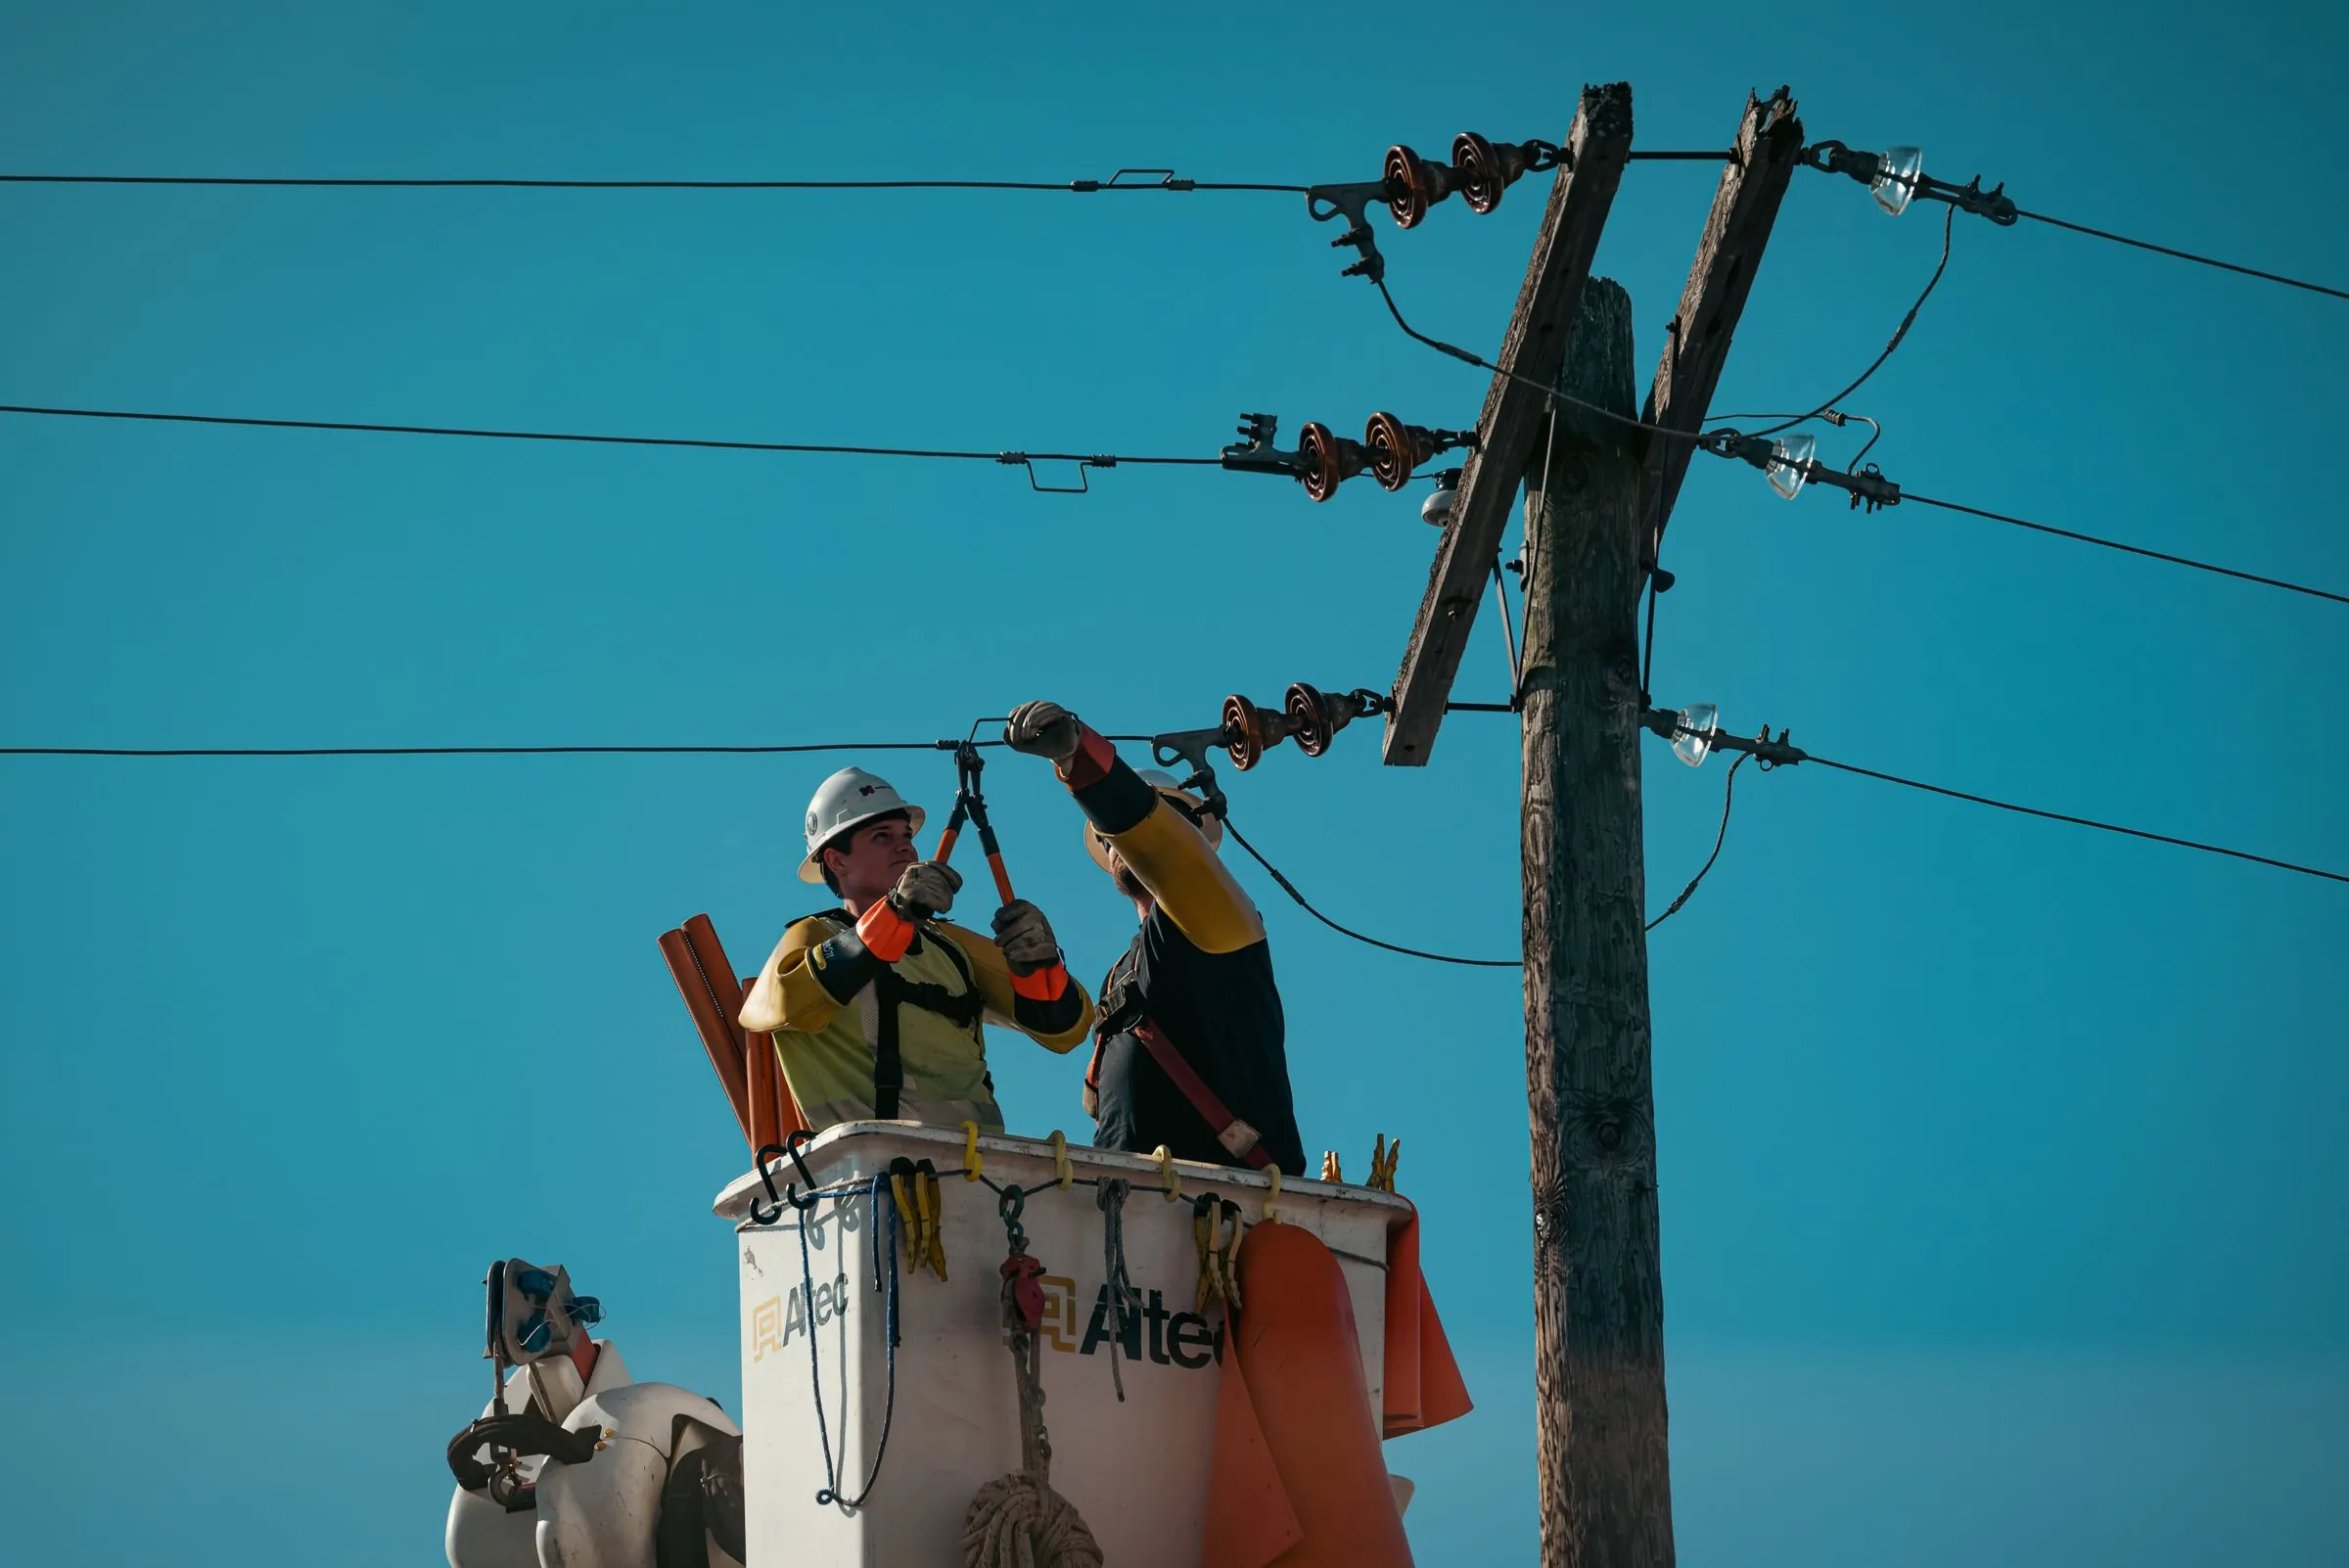
Every light switch, every hospital and every storm cleanup depends on a lineman somewhere up a pole. You keep America's lights on. Let's keep your family covered.
131,900
line workers keeping America's power on
U.S. Bureau of Labor Statistics, Occupational Outlook Handbook — electrical power-line installers and repairers held 131,900 jobs in 2025.
- 2 min
- To check your options
- ~6×
- Line work's fatal injury rate vs. the average job
- $0
- Cost to check
- 49
- States we serve
The problem
Your benefit comes with strings attached
Most linemen have a group or union death benefit. Few have read what it takes to keep it — or figured out how far it would actually go.
It's tied to the job
Group life through a utility or contractor usually ends when the job does, and many union benefits require you to stay in good standing and keep your hours up. A layoff, an injury or a job change can leave a gap at the worst possible time.
It's usually a flat amount
A fixed benefit was built to cover a funeral and a few months of bills — not a mortgage, a truck payment and the next 15 years for your family.
The work is dangerous
Line work has one of the highest fatal injury rates of any trade. Living benefit riders can pay out part of the death benefit if a qualifying illness takes you off the line.
~6×
Line workers' fatal injury rate vs. the average U.S. worker
U.S. Bureau of Labor Statistics, Monthly Labor Review (2018): 19.2–23.9 deaths per 100,000 electrical power-line installers and repairers in 2011–2015, vs. 3.3–3.5 for all workers.
Why linemen own their coverage
Keep your union plan, your pension and your 401(k). This works right alongside them.
01
Yours, not your local's
Many plan and union benefits depend on staying employed and keeping your hours up. A policy you own doesn't care which hall or contractor you're working for.
02
Pay in during storm season
One storm rotation of overtime can fund a whole year. Put it in when the hours are there and dial it back when things slow down, within your policy's limits.
03
Protection when the market drops
Your cash value has a 0% floor, so a bad year in the market credits zero instead of a loss. Policy fees still apply — and we'll show you the down years, not just the good ones.
04
Living benefits
A heart attack, a stroke or a diagnosis that takes you off the line. If you're diagnosed with a qualifying critical, chronic or terminal illness, you can get part of your death benefit early — while you're still alive.
Changing contractors
Your coverage travels with you
Storm work in Florida in September. A new contractor in Texas by spring. Topping out, or hanging up your hooks for good. Your policy goes wherever you go — no local, utility or contractor decides what your family gets, and depending on your age and health, many linemen qualify with no medical exam.
Check my options
Straight answers
Lineman IUL, answered plainly
What is an IUL for linemen?
An IUL is permanent life insurance that provides a death benefit for your family while also giving you the opportunity to build cash value over time. For linemen it's designed around what group and union benefits don't do: it belongs to you, and the premium can flex with storm season and overtime.
My union or employer already covers me. Why would I need this?
Many union and employer death benefits depend on staying employed or keeping up your hours, and pay a fixed amount. A layoff, an injury or a move between jobs can leave a gap. A personally owned policy sits on top of what you already have and doesn't change when your job does. We look at your existing benefit before suggesting anything.
Does it pay if I'm killed on the job?
A life insurance death benefit is paid for death from almost any cause, including an accident at work, subject to the policy's terms — such as the contestability and suicide provisions in the first two years. That is a key difference from an accidental-death-only benefit.
Will line work make my rates higher?
Carriers look at occupation alongside health, and they treat line work differently — some price it as a standard occupation, others less favorably. That variation is exactly why we shop several carriers rather than quoting you one.
Do I need a medical exam?
Not always. Depending on your age, health and the amount of coverage, some carriers can approve you through accelerated underwriting — prescription history, MIB records and your driving record — with no exam at all. Others ask for a short paramedical exam that can be scheduled around your time at home.
What happens if I'm laid off, travel for storm work or change contractors?
Your IUL is personally owned and isn't tied to any employer or local. If work slows down, IULs offer premium flexibility subject to policy requirements — call your agent before reducing payments so the policy is reviewed first and doesn't lapse.
Are you affiliated with my union, local or utility?
No. Prime Financial is an independent insurance agency. We aren't affiliated with any union, local, utility, co-op or contractor — nobody from your local sent us, and nothing about your policy goes through your employer.
No cost, no obligation
See what you qualify for in two minutes
Answer a few quick questions and a licensed agent who works with linemen will put your real numbers together. It's free, there's no pressure, and we'll call when you're on the ground — not up in the bucket.
What happens after you submit
- 1You answer a few quick questionsA handful of questions, about two minutes. No medical exam.
- 2We review your needsA licensed life insurance agent reads it before anything is quoted.
- 3You receive tailored optionsTwo or three carriers, side by side, with the trade-offs named.
- 4An agent calls when you askedYou pick the window. No robocalls, no drip campaign.
About you
Step 1 of 2
Prefer to talk it through?
Mon–Sat, 8am – 8pm CT